Search
Category
Related Industries
- China Soda Ash Producer Inventories Fall to 1.3689 Million Tonnes in Week to October 26China soda ash producer inventories fell 6.94% to 1.3689 million tonnes in the week to October 26. Explore what the drawdown means for procurement planning and supplier delivery checks.
- What determines the cost of professional REACH compliance guidance?REACH compliance guidance cost depends on substance complexity, tonnage, data gaps, and support scope. Discover hidden expenses and compare quotes to build a smarter compliance budget.
- China TDI Price Reaches RMB 40,833 per Tonne on October 25, Up 9.38% in 10 DaysChina TDI price reached RMB 40,833 per tonne on October 25, 2026, up 9.38% in 10 days. Explore market trends and procurement cost implications to inform your purchasing decisions.
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.
China Soda Ash Producer Inventories Fall to 1.3689 Million Tonnes in Week to October 26




Domestic soda ash producer inventories in China fell to 1.3689 million tonnes in the week ending October 26, 2026, according to the supplied news summary. The decline warrants attention from producers, raw material buyers and distributors assessing procurement timing and delivery availability. However, the supplied information identifies no new policy, regulation, standard, certification requirement or trade rule. Its immediate relevance is therefore a market signal that may inform purchasing and contract decisions; it does not establish a change in compliance obligations.
Producer Stocks Decline by 102,100 Tonnes
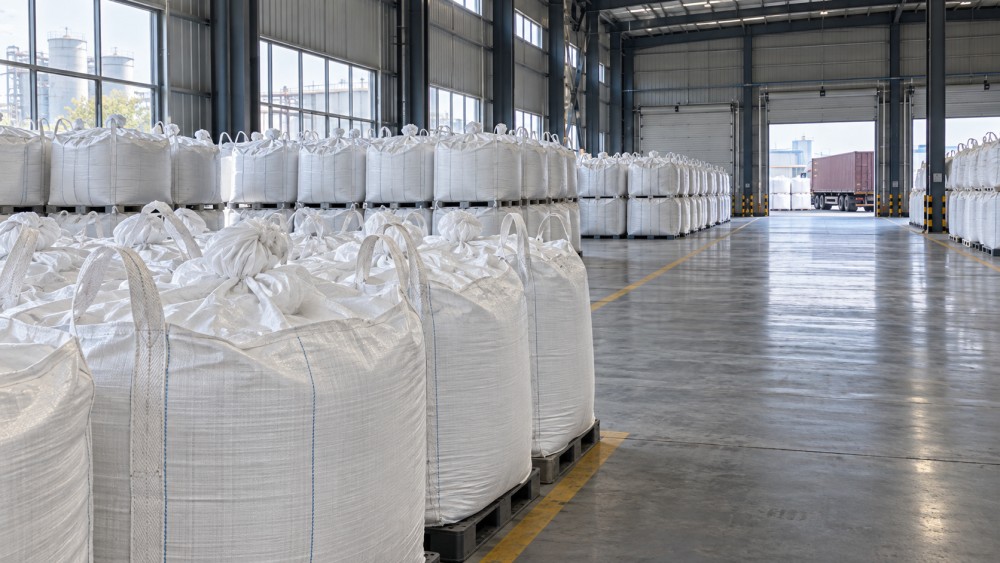
The supplied summary cites an October 26 financial news report drawing on industry inventory data. Domestic soda ash manufacturers held total inventories of 1.3689 million tonnes, down 102,100 tonnes from Thursday, October 22, a decline of 6.94%.
The summary also describes continued substantial inventory drawdowns and links them to some easing of the supply-demand imbalance and the emerging effects of maintenance shutdowns or production cuts.
Procurement and Delivery Terms Deserve Closer Attention
Producers: Check Available Volumes Before Making Commitments
From an industry perspective, falling aggregate inventories may make the relationship between production schedules, available stock and delivery commitments more relevant to sales planning. Producers could review whether quantities offered to customers remain consistent with their own maintenance or production arrangements. The reported national total does not establish the inventory position or delivery capacity of any individual supplier.
Manufacturers: Verify Supply Against Consumption Plans
Analysis suggests that manufacturers purchasing soda ash may benefit from checking supplier availability against their expected consumption and delivery schedules. If maintenance or production cuts affect a selected supplier, order timing or shipment arrangements could require adjustment. The supplied information does not confirm longer lead times, shortages or changes to product specifications, so these points require direct verification.
Distributors and Traders: Confirm Purchase and Resale Commitments
For distributors and trading businesses, a possible consequence is greater attention to whether purchase commitments support promised onward deliveries. Reviewing confirmed quantities, shipment dates and agreed procedures for schedule changes may help assess that exposure. No change to trade documentation, certification or regulatory requirements is established by the inventory figures.
Practical Checks Before Revising Purchasing Plans
Confirm the Supplier-Level Position
As a procurement recommendation, buyers could ask relevant suppliers to confirm available quantities and whether maintenance or reduced output affects outstanding orders. Aggregate inventory data alone cannot establish whether a particular order faces disruption.
Review Delivery Dates and Contract Flexibility
Businesses could assess whether agreed delivery dates remain suitable and whether their contracts address changes in shipment timing or quantities. This is a suggested commercial review, not evidence that contract terms have changed or that new clauses are mandatory.
Keep Compliance Decisions Tied to Verified Requirements
The supplied report offers no basis for changing certification checks, technical documentation or trade compliance procedures. Any proposed change to those arrangements would need separate supporting evidence. If a supplier cites a new regulatory requirement when revising an order, buyers could request the underlying document and verify its scope before treating it as binding.
Use Further Inventory Reports to Test the Signal
As an analytical precaution, procurement teams could compare subsequent inventory movements with supplier confirmations before making substantial purchasing adjustments. The reported decline alone does not establish future availability, price direction or the duration of production restrictions.
The Drawdown Does Not Establish a Regulatory Shift
At this stage, it is more appropriate to understand the report as evidence of an inventory adjustment than as confirmation of a new industry rule. The supplied summary associates the drawdown with maintenance or production cuts, but it does not identify a regulatory cause, mandatory production restriction or implementation timetable.
Further observation would be needed to assess whether inventory reductions persist and whether they affect actual order fulfilment. Any later claim that the movement reflects policy enforcement would require separate verification through the relevant announcement or implementation document. Market data alone cannot establish that connection.
A Basis for Targeted Supply Checks
On the supplied figures, the decline to 1.3689 million tonnes provides a reason to reassess supplier availability and purchasing schedules. Analysis suggests that targeted checks on quantities and delivery commitments are a proportionate response. The report does not support a conclusion that supply shortages are inevitable or that procurement, certification or trade obligations have changed.
Reporting Basis and Points Requiring Follow-Up
This article is based exclusively on the news title, event timing and event summary supplied by the user. Those materials describe an October 26 report citing industry data for the week ending October 26, 2026. The original report and underlying dataset have not been independently verified for this article.
No specific official source link was provided in the input; continued verification is therefore necessary. Relevant follow-up would include subsequent inventory reporting, supplier delivery updates and industry feedback. If a policy, certification or trade-rule explanation is later put forward, the applicable official publication and evidence of its implementation would need to be checked separately.
Recommended News